Benchmark Your Operational Performance Against 1,200+ Peers

Gaining a clear understanding of where you stand compared to your peers can unlock valuable insights and drive strategic improvements.

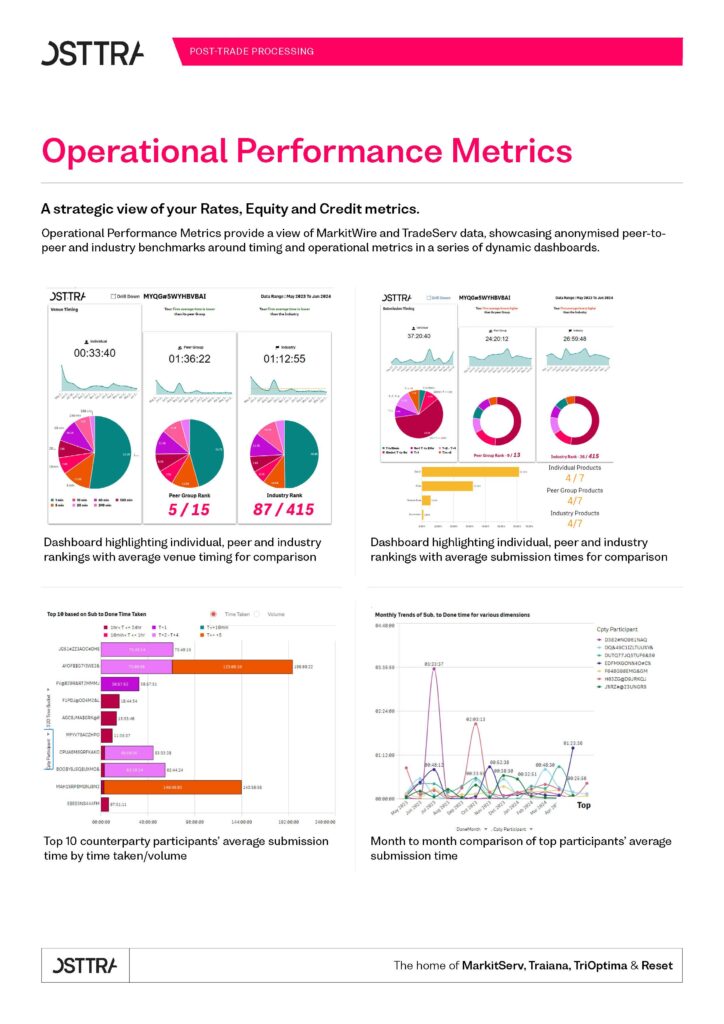
Our new Operational Performance Metrics service empowers you to do just that, offering access to an extensive network of over 1,200 firms across Rates, Equity, and Credit for unparalleled benchmarking capabilities. With fully interactive metrics, you can delve deep into individual asset classes or analyse performance across your entire portfolio on MarkitWire and TradeServ.

This centralised platform provides a strategic view of your operational data, enabling you to:

  1. View Rates, Equity & Credit metrics across legal entities, products and counterparties in one place.
  2. See your operational metrics benchmarked against industry peers to optimise your performance.
  3. Utilise your existing DMS user accounts for a simple and convenient onboarding process.
  4. Have a centralised view of your shared performance metrics for you and your counterparties and customise your data in a way that makes sense for you and your firm.
  5. View your peer and industry rankings per asset class to help improve STP efficiency for that asset class.

Ready to unlock the full potential of your post-trade operations and gain a competitive edge? Download our Operational Performance Metrics factsheet today to learn more about how this new service can help you optimise post-trade efficiency and improve STP rates:


OSTTRA Operational Metrics for MarkitWire and TradeServ data


Discover the power of industry benchmarking and take your post-trade performance to the next level. To discuss your post-trade operational transformation needs, please contact info@osttra.com.

Preparing for further Index Cessation

2023 will see the cessation of the interest rate benchmark that was once the most common in the interest rate swap market – USD LIBOR.

This summary shows how we got here and provides the playbook for the next wave of benchmark with planned cessations evens in 2024.

IBOR reform: LIBOR deadlines, where are we now – global outlook Q1 2022 review continued

JPY Swaps

Background: Japan is taking a multiple rate approach. TIBOR (a.k.a. DTIBOR) is expected to continue alongside TONA. Euroyen TIBOR (a.k.a. ZTIBOR) is planned to be discontinued 2 years after LIBOR cessation. JPY-LIBOR ceased publication on December 31, 2021.

TONA has continued its rise, with 95% of JPY swaps executed in Q1 2022 referencing TONA.


CHF Swaps

Background: CHF-LIBOR ceased publication on December 31, 2021.

Here is how the story unfolded with 100% of single currency interest rate swaps executed in SARON in 2022.


CAD Swaps

Background: Canada is taking a multiple rate approach. Reformed/enhanced CORRA will continue alongside CDOR.

CDOR continues to dominate swap volumes, but CORRA accounted for 8% of CAD swaps executed in the last 6 months. That is nearly triple its historic levels.


AUD Swaps

Background: Australia is taking a multiple rate approach. The reformed BBSW is expected to continue alongside AONIA.

Activity in AONIA has been very subdued for quite some time but after picking up in the second half of 2021, it has grown to almost 10% in the last two months.


SGD Swaps

Background: Singapore initially took a multiple rate approach. However, the reform of SIBOR to base it more on transaction data failed and will cease in 2024. SOR is expected to be replaced by SORA.

SORA has continued its rise, with 98% of SGD swaps executed in March 2022 referencing SORA.


Conclusion

The FCA and most other regulators have been clear, LIBOR and many other IBORs will become extinct in the global swaps market. Progress on adoption of new RFRs has certainly been made, particularly in; SGD (SORA) [c.98%], GBP (SONIA) [100%], CHF (SARON) [100%], JPY (TONA) [c.95%] of new trades are traded on the new RFRs. Elsewhere, AUD (AONIA) [c.10%], CAD (CORRA) [8%], EUR (EuroSTR) [c.20%], and USD (SOFR) [c.60%]. So, while for some currencies the journey is complete, for others the journey continues.


Final thought
With this seismic shift in the products traded in the global OTC derivatives markets, it is reasonable to consider whether there has been any impact on market structure. Well, recently I was approached by a European regulator focussed on the benchmark transition asking when we would be publishing our next update on IBOR versus RFR volumes, (here it is!), and asked whether there is any difference in the trading location data between existing IBORs and the new RFRs. Well to find out the answer, read my piece on the Brexit impact on trading location: Global OTC IRS markets – Q1 2022 review.


Back to beginning

1  2

IBOR reform: LIBOR deadline approaches, flash update on progress in Q4 continued – P2

JPY Swaps

Background: Japan is taking a multiple rate approach. DTIBOR is expected to continue alongside TONA. ZTIBOR is planned to be discontinued 2 years after LIBOR cessation. JPY-LIBOR will cease publication on 31st December, 2021.

TONA has continued its rise, now >70% of JPY swaps executed in November, from 60% in September, up some fifteenfold from 4.5% in June.


CHF Swaps

Background: CHF-LIBOR will cease publication on 31st December, 2021.

SARON has had a significant uptick to almost 80% of CHF swaps executed in November, up from 64% in September, almost trebling from less than 30% in June.


CAD Swaps

Background: Canada is taking a multiple rate approach. Reformed/enhanced CORRA will continue alongside CDOR.

There has been little change with CORRA continuing to make up less than 5% of CAD swaps executed in most months.


AUD Swaps

Background: Australia is taking a multiple rate approach. The reformed BBSW is expected to continue alongside AONIA.

Activity in AONIA has been very subdued over the last 12 months but suddenly increased to 5% of AUD swaps executed in September, October and November, up from 1% in June.


SGD Swaps

Background: Singapore initially took a multiple rate approach. However, the reform of SIBOR to base it more on transaction data failed and will cease in 2024. SOR is expected to be replaced by SORA.

Activity in SORA had been very subdued over the last 12 months but having suddenly increased to over 70% of SGD swaps executed in September, it was over 90% in October and November. This was just 15% in June and less than 5% in May…


Conclusion

The FCA and most other regulators are clear, LIBOR and many other IBORs will become extinct in the global swaps market. Progress on adoption of new RFRs has certainly been made, particularly in; SGD (SORA) [>90%], GBP (SONIA) [>80%], CHF (SARON) [~80%], JPY (TONA) [>70%] of new trades are traded on the new RFRs. There is clearly still a way to go to see the new RFRs completely replace the IBORs in global swaps trading.

There has even been progress in:


What’s next?
With more significant milestone dates approaching we expect to see further shifts in the OTC interest rates swaps landscape. We will be back in 2022…


Back to beginning

1  2

IBOR reform: LIBOR deadline approaches, flash update on progress in Q4

As the deadline for LIBOR cessation in GBP, CHF, JPY and EUR fast approaches we thought we would break our normal cycle of quarterly reviews and assess how much progress has been made in Q4 2021 so far.
Our previous IBOR transition reviews are available here; Q3 2021, Q2 2021 and Q1 2021.


OSTTRA, through its post trade processing service MarkitWire, has been facilitating the migration of legacy cleared portfolios from IBORs to RFRs. MarkitWire has processed over 700,000 trade sides for more than 100 counterparties over several months, including, most recently, over 500,000 trades across the weekend of 4th December as part of the CHF, EUR, JPY CCP LIBOR conversion events. The next major event is the GBP LIBOR conversion event which is set for the weekend of 17th December.

In addition, OSTTRA’s triReduce service has been compressing legacy IBORs as part of its compression service. So far this year, triReduce has compressed almost $55 trillion of notional, for almost 70 entities in the three December 2021 LIBOR cessation currencies GBP, JPY, CHF. Including USD-LIBOR, and dependent currency indices, triReduce compression reached almost $150 trillion of notional, for almost 100 entities in the LIBOR cessation currencies year to date.

OSTTRA has assessed the data processed by our MarkitWire platform to evaluate the progress during Q4 of interbank offered rate (IBOR) transition for the $355 trillion single currency interest rate swaps (IRS) market. Analysing market share in; EUR, GBP, USD, JPY, CHF, AUD, CAD, and SGD between legacy IBORs, legacy / continuing overnight index swaps (OIS) and the new risk-free rates (RFRs).


How has the market share of RFRs evolved since the start of 2020?


GBP Swaps

Background: Reformed SONIA will replace LIBOR which will cease publication on 31 December, 2021.

Reformed SONIA makes up almost 80% of new trades executed. However, this has barely changed since August…


….and over 90% of the notional traded.


EUR Swaps

Background: EuroSTR (a.k.a. €STR) will replace EONIA. There was an initial uptick at the end of July 2020 driven by the CCPs switching from EONIA to EuroSTR discounting on 25th July 2020. It is expected that EURIBOR will continue to be published until at least 2025 but that there will be a material migration to EuroSTR. EUR-LIBOR will cease publication on 31st December, 2021 but it is not traded in the swaps market, there have been <10 trades a month for many years.

EuroSTR has jumped from 4.5% of EUR swaps executed in September, to 15% in November. As EONIA fell from 12% to 0%. Remember EuroSTR was just 2.8% in June 2021!


… and approximately a quarter of notional traded, up from 7% in September!


USD Swaps

Background: SOFR will replace Fed Funds and USD-LIBOR, although the ARRC have recently approved a Term-SOFR whose adoption will be interesting to watch… There was an initial uptick in SOFR at the end of October 2020 driven by the CCPs switching from Fed Funds to SOFR discounting on 16th October 2020. Unlike the other LIBORs, it is expected USD-LIBOR will continue to be published until June 30, 2023, albeit “SOFR first” applied to interdealer swaps from 26th July 2021.

SOFR has continued its charge, with the SOFR first initiative driving SOFR up to 26% of USD swaps executed in November, versus 17% in September, and up some eightfold from 3% in June. BSBY swaps have traded every month since September but remain <0.01%!


… and approximately 30% of notional


IBOR reform: LIBOR deadlines, where are we now – global outlook Q1 2022 review

As the deadline for LIBOR cessation in GBP, CHF, JPY, and EUR passed in December 2021 we thought we would take a look at the data to get the latest picture of global IBOR reform as of Q1 2022.
Our previous IBOR transition reviews are available here: Q4 2021, Q3 2021, Q2 2021 and Q1 2021.


OSTTRA through its post trade processing service MarkitWire facilitated the migration of legacy cleared portfolios from IBORs to RFRs in CHF, EUR, GBP and JPY as part of the CCP LIBOR conversion events. MarkitWire processed over 1,000,000 trade sides for over 100 counterparties, through its CCP Synchronization service, over several months culminating in the final GBP run on December 17th.  The industry is now busy preparing for the USD transition that will take place mid-2023.  The OSTTRA team is already discussing this transition with impacted stakeholders and will be ready to support all events linked to the transition, including the highly anticipated transition dry runs.

In addition, OSTTRA’s triReduce service compressed legacy IBORs as part of its compression service. In Q1 2022, triReduce has compressed its largest amount of USD notional since 2018 reaching $32 trillion for over 50 entities which also includes dependant currency indices (SGD and THB).

OSTTRA has assessed the data processed by our MarkitWire platform to evaluate the progress of interbank offered rate (IBOR) transition for the $355 trillion single currency interest rate swaps (IRS) market. Analysing market share in; EUR, GBP, USD, JPY, CHF, AUD, CAD, and SGD between legacy IBORs, legacy / continuing overnight index swaps (OIS) and the new risk-free rates (RFRs).


How has the market share of RFRs evolved since the start of 2020?


GBP Swaps

Background: Reformed SONIA has replaced LIBOR which ceased publication on 31 December, 2021.

Here is how the story unfolded with 100% of single currency interest rate swaps executed in SONIA in 2022.


EUR Swaps

Background: EuroSTR (a.k.a. €STR) has replaced EONIA. It is expected that EURIBOR will continue to be published until at least 2025 but that there will be a material migration to EuroSTR. EUR-LIBOR ceased publication on December 31, 2021 but hadn’t been materially traded in the swaps market for at least a decade.

EuroSTR has jumped to over 20% of EUR swaps executed. Much of this came from EONIA’s demise but EURIBOR has fallen from just under 90% to just under 80% over the past 6 months.


… and approximately 60% of notional traded.


USD Swaps

Background: SOFR will replace Fed Funds and USD-LIBOR, although the ARRC have approved a Term-SOFR whose adoption will be interesting to watch… There was an initial uptick in SOFR at the end of October 2020 driven by the CCPs switching from Fed Funds to SOFR discounting on 16th October 2020. Unlike the other LIBORs it is expected USD-LIBOR will continue to be published until June 30, 2023, albeit “SOFR first” applied to interdealer swaps from 26th July 2021.

SOFR has continued its charge, over 60% of new USD swaps executed in March 2022 referenced SOFR, continuing a month-by-month march forward. BSBY swaps, a credit sensitive rate, have traded every month since September but remain <0.1%.

IBOR reform: USD LIBOR deadline, the big one approaches…

SOFR dollar swaps surge to new record as transition deadline looms

A record 85% of USD swaps referenced the Secured Overnight Financing Rate (SOFR) benchmark in March, according to data from OSTTRA. This comes at a critical milestone in the transition to Risk-Free Rates (RFRs), with USD London Interbank Offered Rate (LIBOR) due to expire in less than 90 days (30 June 2023).

The growth in the volume of USD SOFR referenced swaps executed in March continues a steady month-by-month progression for the new derivative contracts, rising 23% over the last 12 months from 62% in March 2022.

The increased adoption of SOFR – an alternative rate to LIBOR that measures the cost of borrowing cash overnight collateralised by US Treasuries – comes in response to the decision to discontinue LIBOR following concerns surrounding the benchmark rate’s reliability and accuracy.

OSTTRA, through its post trade processing and compression services, helps firms smoothly transition from legacy IBORs to RFRs including playing a crucial role in enabling firms to manage the migration of legacy cleared portfolios.

“This data paints an encouraging picture of the industry’s progress in transitioning away from LIBOR,” says Kirston Winters, Chief Risk Officer at OSTTRA. “As we saw with the successful departure from IBOR across mainstream markets such as the UK and Japan, the operational burden in delivering this kind of switch is certainly manageable and can even be executed smoothly. That said, we haven’t reached the finish line just yet – a wide variety of key market participants must continue to cooperate effectively over the coming months, as we enter the final critical stage of this historic migration.”


Read the full report

Brexit Impact on Trading Location: Global OTC IRS Markets – Q1 2023 Review

US Races Ahead of EU in Post-Brexit Euro Swaps Trading

As Brexit continues to dent London’s historic dominance of euro swaps trading, the majority of on-venue business is fleeing to Wall Street, not Europe.

New data from OSTTRA MarkitWire found London trading venues’ share of the euro interest rate swap market slipped to just 14% in March. In the same period, US market share of on-venue euro swaps was 51%, the highest recorded share. In contrast, EU venues had just over a third (35%) – their lowest share since December 2020.

The findings are the latest sign of the repercussions on the City from Brexit, which cut off access to most London trading from the bloc. The data shows a continual downward drift since the UK officially left the Single Market back in January 2021. So far this year, the UK venues’ average is just 15%, down from 16% in 2022, and 17% in 2021. Prior to leaving the EU, UK market share for euro interest rate swaps trading was north of 70%.

“While market share is certainly one aspect of this post-Brexit story, market access is the other,” according to Kirston Winters, Chief Risk Officer at OSTTRA. “Certain EU and UK banks, as well as EU and UK investment managers, have significantly reduced market access for transactions that are subject to an EU or UK derivatives trading obligation.

The reality is that many clients in the UK are unable to trade on EU venues, and vice versa. This means that to trade certain derivative products on UK venues, firms must either stay in their home market or utilise a US swaps execution facility (SEF) venue to gain broader liquidity, unable to access the other European market available. The swap markets may have previously been truly global, but it is now very much fragmented.”


Read the full report

IBOR reform: USD LIBOR deadline, the big one approaches…

As the deadline for USD LIBOR cessation fast approaches, we took a look at the data to get the latest picture of global IBOR reform as of the end of Q1 2023.

OSTTRA through its post trade processing service MarkitWire first facilitated the processing of Secured Overnight Financing Rate (“SOFR”) swaps in July 2018. The first migration of legacy cleared portfolios from USD-LIBOR to SOFR were processed by OSTTRA MarkitWire on the weekend of 22 April 2023. This included trades cleared at Eurex, CME Group and LCH. OSTTRA MarkitWire processed over 250k trades for over 150 counterparties, through its CCP Synchronization service. The main LCH USD conversion and the HKEX conversion is scheduled for 20 May 2023. OSTTRA MarkitWire will also process trades as part of the conversation for dependant currency indices (SGD and THB) in June 2023. The conversion for USD is considerably larger than previous conversions in GBP, EUR, CHF and JPY.

In addition, OSTTRA triReduce has continued to compress legacy USD-LIBOR swaps as part of its compression service. In 2023 OSTTRA triReduce has compressed $8.474 trillion of notional, for 68 entities which also includes dependant currency indices (SGD and THB).

OSTTRA has assessed the data processed by OSTTRA MarkitWire to evaluate the progress of interbank offered rate (IBOR) transition for the $414 trillion single currency interest rate swaps (IRS) market. Analysing market share in USD and CAD between legacy IBORs, overnight index swaps (OIS) and the new risk-free rates (RFRs).

USD swaps

Background:

As the deadline approaches SOFR has continued its charge, a new record of 85% of new USD swaps executed in March 2023 referenced SOFR, continuing a month-by-month progression.


In terms of notional traded, SOFR has been consistently around 40% for the last few months due to Fed funds maintaining around 50% share by notional.

CAD Swaps

Background:
Canada is taking a multiple rate approach. Reformed/enhanced CORRA will continue alongside the incumbent CDOR.

CDOR continues to dominate swap volumes, but CORRA has progressed strongly in Q1 2023 with a record share of trade count at 28% of CAD swaps executed in March 2023. That is nearly triple its historic levels.


In notional traded terms CDOR has been the majority since November 2022 with March 2023 marking a new record of almost 70%.


Conclusion

As the transition of USD-LIBOR approaches, despite the evident progress to date, their remains much to be done in the time remaining. With the experience gained in other currencies such as GBP, EUR, CHF and JPY the industry is well placed to ensure smooth transition.

IBOR reform: LIBOR deadlines, where are we now – global outlook Q1 2022 review

As the deadline for LIBOR cessation in GBP, CHF, JPY, and EUR passed in December 2021 we thought we would take a look at the data to get the latest picture of global IBOR reform as of Q1 2022.
Our previous IBOR transition reviews are available here: Q4 2021, Q3 2021, Q2 2021 and Q1 2021.


OSTTRA through its post trade processing service MarkitWire facilitated the migration of legacy cleared portfolios from IBORs to RFRs in CHF, EUR, GBP and JPY as part of the CCP LIBOR conversion events. MarkitWire processed over 1,000,000 trade sides for over 100 counterparties, through its CCP Synchronization service, over several months culminating in the final GBP run on December 17th.  The industry is now busy preparing for the USD transition that will take place mid-2023.  The OSTTRA team is already discussing this transition with impacted stakeholders and will be ready to support all events linked to the transition, including the highly anticipated transition dry runs.

In addition, OSTTRA’s triReduce service compressed legacy IBORs as part of its compression service. In Q1 2022, triReduce has compressed its largest amount of USD notional since 2018 reaching $32 trillion for over 50 entities which also includes dependant currency indices (SGD and THB).

OSTTRA has assessed the data processed by our MarkitWire platform to evaluate the progress of interbank offered rate (IBOR) transition for the $355 trillion single currency interest rate swaps (IRS) market. Analysing market share in; EUR, GBP, USD, JPY, CHF, AUD, CAD, and SGD between legacy IBORs, legacy / continuing overnight index swaps (OIS) and the new risk-free rates (RFRs).


How has the market share of RFRs evolved since the start of 2020?


GBP Swaps

Background: Reformed SONIA has replaced LIBOR which ceased publication on 31 December, 2021.

Here is how the story unfolded with 100% of single currency interest rate swaps executed in SONIA in 2022.


EUR Swaps

Background: EuroSTR (a.k.a. €STR) has replaced EONIA. It is expected that EURIBOR will continue to be published until at least 2025 but that there will be a material migration to EuroSTR. EUR-LIBOR ceased publication on December 31, 2021 but hadn’t been materially traded in the swaps market for at least a decade.

EuroSTR has jumped to over 20% of EUR swaps executed. Much of this came from EONIA’s demise but EURIBOR has fallen from just under 90% to just under 80% over the past 6 months.


… and approximately 60% of notional traded.


USD Swaps

Background: SOFR will replace Fed Funds and USD-LIBOR, although the ARRC have approved a Term-SOFR whose adoption will be interesting to watch… There was an initial uptick in SOFR at the end of October 2020 driven by the CCPs switching from Fed Funds to SOFR discounting on 16th October 2020. Unlike the other LIBORs it is expected USD-LIBOR will continue to be published until June 30, 2023, albeit “SOFR first” applied to interdealer swaps from 26th July 2021.

SOFR has continued its charge, over 60% of new USD swaps executed in March 2022 referenced SOFR, continuing a month-by-month march forward. BSBY swaps, a credit sensitive rate, have traded every month since September but remain <0.1%.

Services