Energy Market Risks Have Not Been Learned from 2022

The lesson energy markets should have learned from the 2022 European energy crisis is straightforward – optimisation is not just for periods of stress, but embedded in everyday market practice.

Energy markets are facing a sustained period of elevated uncertainty, that is showing no signs of easing. The industry has repeated an old mistake of treating credit risk and liquidity management as a reactive measure rather than a routine discipline. While energy firms are more robust now than four years ago, it is unclear whether the market could withstand a similar shock today.

The 2022 crisis was triggered by a severe physical shock. Europe lost a significant share of its gas supply as Russian flows collapsed which sent prices soaring to unprecedented levels. But while the origins of the crisis were physical, the severity of the disruption exposed financial vulnerabilities across the market. Margin requirements surged well beyond market stress tests and ultimately required some governments to intervene in supporting energy firms.

The price rises caught the headlines, but behind the scenes the real problem was in liquidity and credit risk management. The crisis played out over several months, but it had been building for years, as firms entered the period without sufficient resilience.

It is tempting to assume that the market is now better prepared. Europe has diversified supply, expanded LNG capacity, and reduced reliance on single sources of energy. These meaningful improvements should mitigate the risk of a repeat supply shock. However, they do little to address the financial mechanisms that amplified the last crisis. When volatility rises, margin calls follow and firms are not well-placed to adapt to this.


The recent energy market shock caused by the conflict in the Middle East caused credit risk to increase. Firms prioritised access to liquidity, as shown by large trading houses securing credit facilities to meet potential collateral demands. But just because firms were able to cope does not mean risk is being managed efficiently.

The underlying issue is that much of the energy market still approaches optimisation of credit and liquidity on an ad hoc basis. In stable conditions, it is often deprioritised. When volatility spikes, attention returns to credit and liquidity. By then, much of the cost is already locked in. Optimisation is most effective when it is continuous, not when it is deployed in response to stress.

This challenge is particularly acute in energy markets because of its structure. Unlike banks or large financial institutions, energy firms typically are limited in their credit options. Cash is expensive, with many energy firms rated in the high yield bracket. And while letters of credit are widely used in bilateral markets, they do not eliminate risk.

In periods of stress, breaching credit limits can restrict trading and potentially force liquidations. Firms without sufficient access to funding may come under pressure regardless of the quality of their underlying positions. Larger participants may be better able to withstand this, but smaller firms could face disproportionate challenges.

Optimisation involves determining full portfolio risk, in both cleared and bilateral contracts and positions in other related assets. Firms can end up posting significant margin on positions while holding offsetting exposures elsewhere in their portfolios. The result is unnecessary liquidity pressure.

The key lesson is that optimisation should be treated as a normal part of risk management. It should sit alongside hedging, collateral management and credit control as a continuous process. Over the regular course of trading, firms will take on more liquidity and credit risk than their net overall positions require. Regular cycles of optimisation keep that to a minimum.

Importantly, risk in energy markets is not confined to extreme events. Over the first quarter of 2026, initial margin for front month contracts rose 50%.

Energy firms also face higher credit risk, as the need to physically deliver the power or gas pushes them to bilateral and over-the-counter trading. Credit risk therefore needs to be proactively managed and portfolios continuously optimised.

With two energy shocks in the past four years, firms need to take more seriously the importance of optimisation. Emergency management of credit and collateral risk in times of crises has proven to be inadequate, with the worst-case scenario requiring government intervention. By making credit optimisation a day-to-day practice, firms can reduce risk in more benign times and keep more options open whenever the next shock arises.

To learn more about how OSTTRA Rebalance can help optimise your energy derivatives portfolio, contact us below or click here.


This article was originally published by FOW.
Mitigating Energy Portfolio Risk: Why Proactive Optimisation is Essential

In modern energy risk management, there is no such thing as a “safe” price direction. Whether the forward curve climbs, plateaus, or drops, every trajectory carries unique liquidity and credit risks for trading firms.

As market volatility persists, relying on reactive measures is no longer sufficient. Firms must proactively insulate their portfolios to manage exposure and prevent costly limit breaches.

The impact of price movements

Regardless of market direction, unoptimised portfolios quickly accumulate significant financial resource constraints:

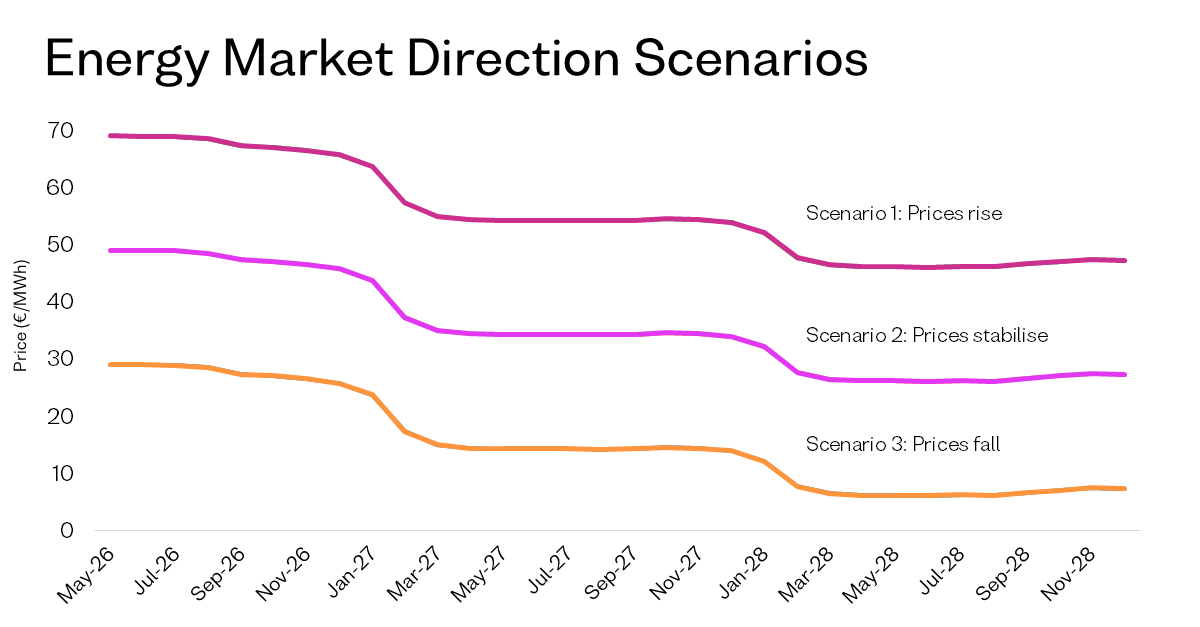
  • Scenario 1 – Prices rise: Initial Margin (IM)/ variation margin (VM) increases and liquidity risk materialises. Bilateral MTM/VM exposures cause limit breaches. New trades at high prices lock in significant settlement risk.
  • Scenario 2 – Prices stabilise: IM/VM and bilateral MTM exposure remains elevated. Trades at elevated prices continue to build up bilateral settlement risk.
  • Scenario 3 – Prices fall: High priced trades drive high bilateral and exchange VM. Settlement risk is elevated until high price trades roll off. The longer prices remain high, the more pronounced these risks become.

Mitigating risk through multilateral optimisation

To prepare your business from whatever tomorrow’s curve looks like, continuous portfolio optimisation is essential.

OSTTRA Rebalance provides a highly scalable and consistent optimisation process specifically designed to tackle modern energy trading risk. Our algorithm systematically targets numerous risk metrics simultaneously, enabling comprehensive risk reduction across exchange and bilateral markets that is necessary in an increasingly complex market environment.

This process allows participants to rebalance their portfolios without altering market risk profiles, effectively freeing up credit lines and reducing the funding costs associated with volatile margin calls.

Build a more resilient portfolio against price swings

Irrespective of market conditions, proactive optimisation provides a clear path to reduced risk and lower costs.

To learn more about how OSTTRA Rebalance can help optimise your energy derivatives portfolio, contact us below or click here.

Beyond DORA: Building a Foundation for Lasting Operational Resilience in Post-Trade

The DORA deadline on the 17th of January 2025 is a critical milestone for financial firms operating in the EU. But achieving true operational resilience goes beyond headline risks like cyber risk and checking boxes for compliance. It requires a proactive and holistic approach that anticipates and mitigates a wide range of potential disruptions.

In this video, OSTTRA experts go beyond the immediate demands of DORA to explore the broader landscape of post-trade operational resilience. They discuss:

Post-Trade Dictionary: Decode Industry Terms from A to Z with this Post-Trade Glossary

Opposing Enron Effect on Energy Trading Puts Credit Risk Under the Spotlight

Twenty-two years ago this month, the collapse of Enron sent shockwaves across various segments of the global financial industry. The accounting scandal which saw Enron, an energy trading company, collapse and thus default on its book of energy market trades left those on the other side of the trade with significant credit risk. This was the first domino to fall that led to centralised clearing for US energy markets, as market participants sought the safety net offered by clearing houses. What we see now is an US energy market whereby most of the trading in derivatives involves cleared futures on an exchange.

Across the pond in Europe and we have a completely different picture altogether. With a seismic event, in the form of an Eastern European war, hitting the energy markets so drastically over the past two years, it’s a miracle we haven’t seen more energy trading companies collapse under the strain. While governments stepped in to rescue, this does not change the fact that one or two firms were right on the brink. The market generally understood that major disaster was not far away, and this subsequently has put a greater focus on credit risk.

Overall, exposures of EU entities to energy derivatives markets totalled around €1.1 trillion (£950bn) in February 2023, with natural gas and power derivatives representing 60% of the gross notional amounts (Source: ESMA paper on EU Energy Derivatives Markets: Structure and Risks). This is a staggeringly large market, second to FX for bilateral volumes, which means there is a high amount of credit risk. This raises the question – is it time European energy markets shifted from a bi-lateral to a cleared world?

No crisis, regardless of how big the knock-on-effect is, will change the fact that energy trading firms prefer to use OTC derivatives for specific risk management needs tailored to their physical operations. The reality is that central clearing does not always support all the products or structures required by energy traders. At the moment, with European energy markets as volatile as they are, listed derivatives mean posting high amounts of margin which would be far too costly for most firms. This is why the majority of the market stills prefers to maintain flexibility by using bilateral OTC contracts. In fact, certain firms have even managed to net down exposure in clearing and replaced it with additional bi-lateral exposure which does not require initial margin to be posted.

Therefore, with clear evidence to suggest that energy trading will remain bilateral for the foreseeable future, attentions must now turn to how credit risk can be managed as and when the next unexpected event materialises. A handful of banks aside, the market is still not subject to any capital requirements, yet it is still very much exposed to credit risk which, if not managed correctly, could lead to numerous defaults.

“The sheer size of the bilateral energy trading market means there are still significant credit risks that need to be managed, and effective credit risk management is crucial for energy trading firms to ensure the continuity of their trading activities.”

From ongoing credit assessments, to stronger risk mitigation measures and continual credit monitoring to minimise the impact of counterparty defaults, energy trading firms now need to manage their bi-lateral exposure in a way that is a reliable alternative to clearing but without the costs of posting margin. This is why, since the volatility has calmed somewhat, we have seen more firms turn to tools that enable their bi-lateral credit exposures to be managed down on a relatively continuous basis by offsetting exposures on a multilateral basis.

While certain energy trading firms may not be worried about credit risk due to having collateral agreements in place with major counterparties, this does not alter the fact that they are still exposed if there are any significant changes in market prices due to unforeseen events, such as the recent threat of strike at an two of Chevron’s Australian LNG plants which sent the price of the Dutch TTF hub soaring 10% in a day.

Moves to reduce credit risk are especially important right now given the structural instabilities in energy markets today, caused by a number of factors, including an unreliable supply of gas and the transition to greener more sustainable alternatives. Ultimately, if energy trading is to remain bi-lateral, then no stone can be left unturned when it comes to managing credit risk exposures across the different counterparties. The Enron collapse might seem like a distant memory, but the fallout 22 years ago is still a good lesson to manage credit risk carefully.

Services